Last updated: 2026-10-16
Walking into a bank to ask for money when you have no credit history feels like trying to find your way through a pitch-black room without a flashlight. If you have never owned a credit card or financed a car, traditional banks might treat you like a ghost. It is a frustrating cycle where you need a history of credit just to prove you are worthy of it.
This financial Catch-22 leaves many people in limbo. Young professionals, recent immigrants, and those trying to recover from a past financial setback often find themselves locked out of the very tools needed to build a stable life. It can feel like the system is designed to keep you on the sidelines.
Fortunately, the way lenders look at your wallet has changed this year. Lenders are moving away from staring at a single FICO number to decide your fate. Instead, they are looking at your actual income, how steady your job is, and your overall financial habits. Your utility bills and rent history now carry much more weight than they did five years ago.
By looking at the whole picture rather than just one score, lenders can extend credit to millions of people who were previously considered unscorable. This shift toward alternative data means your paycheck and consistent bills are your new best friends in the eyes of a loan officer.
When we built this ranking, our main goal was finding accessibility for people without a credit footprint. We searched for lenders that offer “soft pulls” or pre-qualification steps. This is a vital distinction. A soft pull lets you see your potential terms without any risk to your score. You can “window shop” for rates without any penalty.
A “hard inquiry” is different. That happens when a lender digs deep into your credit report to make a final decision, and it can shave points off your FICO score. By prioritizing companies that use soft pulls during the initial phase, we tried to protect your growing credit history from unnecessary damage.
Speed and transparency were the next big things we checked. A lender that hides fees in the fine print or waits two weeks to deposit your money is useless if you are facing an emergency. If a car transmission fails or a medical bill arrives, you need cash, not excuses. We looked for companies that provide clear amounts, quick funding, and easy ways to talk to a human.
We also insisted on lenders that clearly state their APR. This number is the real truth because it includes both the interest rate and any mandatory fees. Knowing the APR gives you a genuine look at how much this loan will actually cost you over time.
We also looked at whether a loan acts as a tool for growth or a trap for debt. We favored lenders that offer predictable monthly payments. Avoid anyone using predatory interest structures that can lead to a debt spiral. We studied the difference between simple interest and compounding interest, as the latter can make your debt balloon much faster than you expect.
| Lender Name | Loan Amounts | Funding Speed | Credit Impact Check | Minimum/Max Terms |
|---|---|---|---|---|
| JetzLoan | $500 – $35,000 | As little as 24 hours | No hard credit pull | see site |
| Discover | $2,500 – $40,000 | As early as next business day | No impact to credit score | see site |
| OppLoans | see site | Same-day funding available | Does not affect FICO score | see site |
| OneMain Financial | $1,500 – $30,000 | As soon as 1 hour after signing | No credit score impact | 24-60 months |
| Coastline Credit Union | see site | see site | see site | see site |

JetzLoan helps people who are trying to navigate the tricky waters of a thin credit file. By connecting you with various top lenders, they make the search much simpler. It is a great choice if you need cash fast for an unexpected car repair or to consolidate some urgent debt.
Instead of wasting hours applying to ten different places and risking ten different hard inquiries, JetzLoan gathers your options into one single, streamlined experience. This saves you time and protects your score while you are still figuring out your options.
The application is quick, usually taking about two minutes. Since they use a “no hard credit pull” model during the start, you can explore without any fear. You can see if you qualify for up to $35,000 without any pressure. This is perfect for first-time borrowers who are still learning how to read loan offers and don’t want to mess up their standing before they truly understand the fine print.
Pros: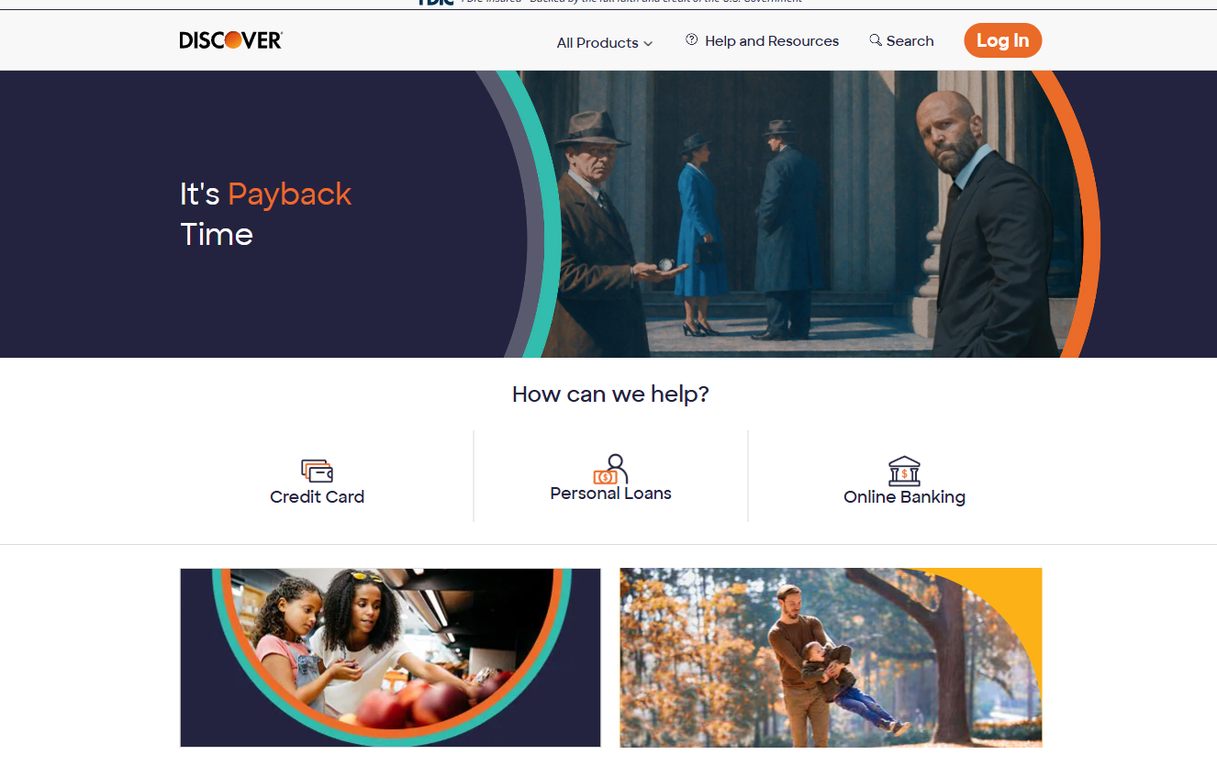
Discover is a massive name in banking, offering the kind of stability many new borrowers want. Their personal loans are built for people looking for a long-term financial partner, not just a quick check. With rates starting as low as 6.99% APR, they provide a real path to growth.
If you are moving from “no credit” to “rebuilding,” Discover offers a structured environment that rewards you for paying on time. They have a very clear pre-approval process that won’t touch your credit score. If you get the green light, the money can be in your account as early as the next business day.
They are a reliable choice for anyone with steady income who wants to work with a major institution. Because they are so large, their digital tools are excellent. You can manage your payments, check statements, and track your progress through a very smooth mobile app.
Pros:
OppLoans is designed for the person who has heard “no” from every big bank in town. They look past the traditional FICO score to find reasons to say “yes” to you. This makes them a vital resource for those just starting out or those who have faced a recent hiccup, like a medical emergency or a temporary job gap.
They care about your current ability to pay, often looking at your bank account activity rather than just a static number from a bureau. The platform is built for speed, and you might even see same-day funding. It is a much safer way to get cash than the payday loan industry.
Payday loans are notorious for astronomical interest rates that can exceed 400% APR, which often traps people in a cycle of debt. OppLoans provides a structured alternative. You get a way to manage your needs without the predatory terms and hidden fees that make other quick-cash options so dangerous.
Pros:
OneMain Financial offers a mix of digital ease and human connection. If you would rather talk to a real person than a chatbot, their 1,300 branches are a huge benefit. This is perfect if you want to sit down with someone to explain a specific situation, like a one-time change in your income.
That human element can be the difference between a denial and an approval. They offer flexible terms from 24 to 60 months, so you can tailor the monthly payment to fit your budget. With loans starting at $1,500, they work for everything from small home fixes to larger debt consolidation.
The speed is impressive too. You could have funds available just one hour after signing. It is rare to find that kind of speed from a lender that has such a large physical presence across the country.
Pros:
Credit unions are often the best-kept secret for people new to borrowing. Coastline Credit Union uses a member-focused model, which usually leads to more personalized service. Unlike big banks that exist to satisfy shareholders and drive quarterly profits, credit unions are cooperatives owned by their members.
Their primary goal is to serve the community, which often results in more lenient underwriting for local residents. While you might have to meet certain membership requirements—like living in a specific county or working in a certain field—the perks are often worth it. They offer various loan solutions and digital tools to help you manage your money.
It is a “slow and steady” way to build a financial foundation. The lender is actually invested in your long-term success, not just how much interest they can squeeze out of you this month.
Pros:When you look at loan offers, you will see two different types of numbers. You need to know the difference to avoid getting burned. The first is the Simple Interest Rate, which is just the basic cost of borrowing the principal. But that does not tell the whole story of what you will actually pay.
The second, and much more important, number is the Annual Percentage Rate (APR). The APR includes the interest rate plus any other costs needed to get the loan, like origination fees or documentation fees. This is the number that actually matters for your wallet.
For instance, if you take a $5,000 loan at a 10% interest rate, but the lender charges a $500 “processing fee,” your APR is much higher than 10%. Always use the APR when comparing two different lenders. If Lender A has a 7% rate but high fees, and Lender B has an 8% rate with no fees, Lender B is actually the cheaper choice. Do not let a low “headline” interest rate distract you from the total cost shown in the APR.
If you are new to this, stick to these three rules to keep your financial health intact:
Before you hit “apply,” have a clear plan. Borrowing money is a commitment to a repayment schedule, not just a way to get quick cash. Calculate exactly what you need so you don’t over-borrow. It is much easier to pay off a small loan than a massive one. Many people borrow the maximum amount just to have a “safety net,” but they end up paying interest on money they never even needed.
Don’t just look at the monthly payment. Look at the APR and the total amount you will pay over the life of the loan. A low monthly payment often means a much longer term, which can cost you thousands in interest. Use an online calculator to see how changing your payment by even $25 a month can save you hundreds of dollars in the long run.
Gather your documents before you start. Even if a lender says they don’t need a hard credit check, you will eventually need to prove your identity and income to finish the contract. Have your recent pay stubs, bank statements, and ID ready to go. If you are consolidating debt, have those creditor statements ready too; some lenders can pay them directly, which makes the whole process much smoother.
Thêm nữa
Bạn có quan điểm riêng về “Rượu vang đỏ – thức uống có lợi cho sức khỏe?” Hãy gửi liên hệ tới chúng tôi theo hướng dẫn phía dưới ⇓ để cùng chia sẻ và thảo luận về rượu vang